Key Takeaways
- A payment gateway enables secure online payments by transmitting payment information between customers, businesses, banks, and payment networks for transaction authorisation.
- Payment gateways support multiple payment methods, including UPI, credit cards, debit cards, net banking, and digital wallets, allowing businesses to offer customers flexible payment options.
- Payment gateways use encryption, tokenisation, authentication, and fraud monitoring to protect sensitive payment information and support secure digital transactions.
- Businesses can integrate payment gateways through APIs, SDKs, or plugins for websites, mobile apps, and e-commerce platforms such as Shopify, WooCommerce, and Magento.
- Choosing the right payment gateway depends on transaction charges, payment success rates, settlement timelines, security, and integration flexibility. Businesses should also evaluate reporting, reconciliation, and customer support to ensure reliable payment operations.
What is a Payment Gateway?
A payment gateway is a technology that securely processes online payments between customers, businesses, and banks. It encrypts sensitive payment data, authorizes transactions in real time, and enables businesses to accept payments through credit cards, debit cards, UPI, net banking, wallets, and other digital payment methods.
It captures payment information at checkout, encrypts sensitive details, and forwards the request to banks and payment networks for authorization. After verification, the gateway confirms whether the payment is successful or failed and shares the status with both the customer and the merchant. Payment gateways are used by websites, mobile apps, and e-commerce platforms to accept payments through cards, UPI, net banking, and digital wallets.
Integrate a Payment Gateway
How a Payment Gateway Works
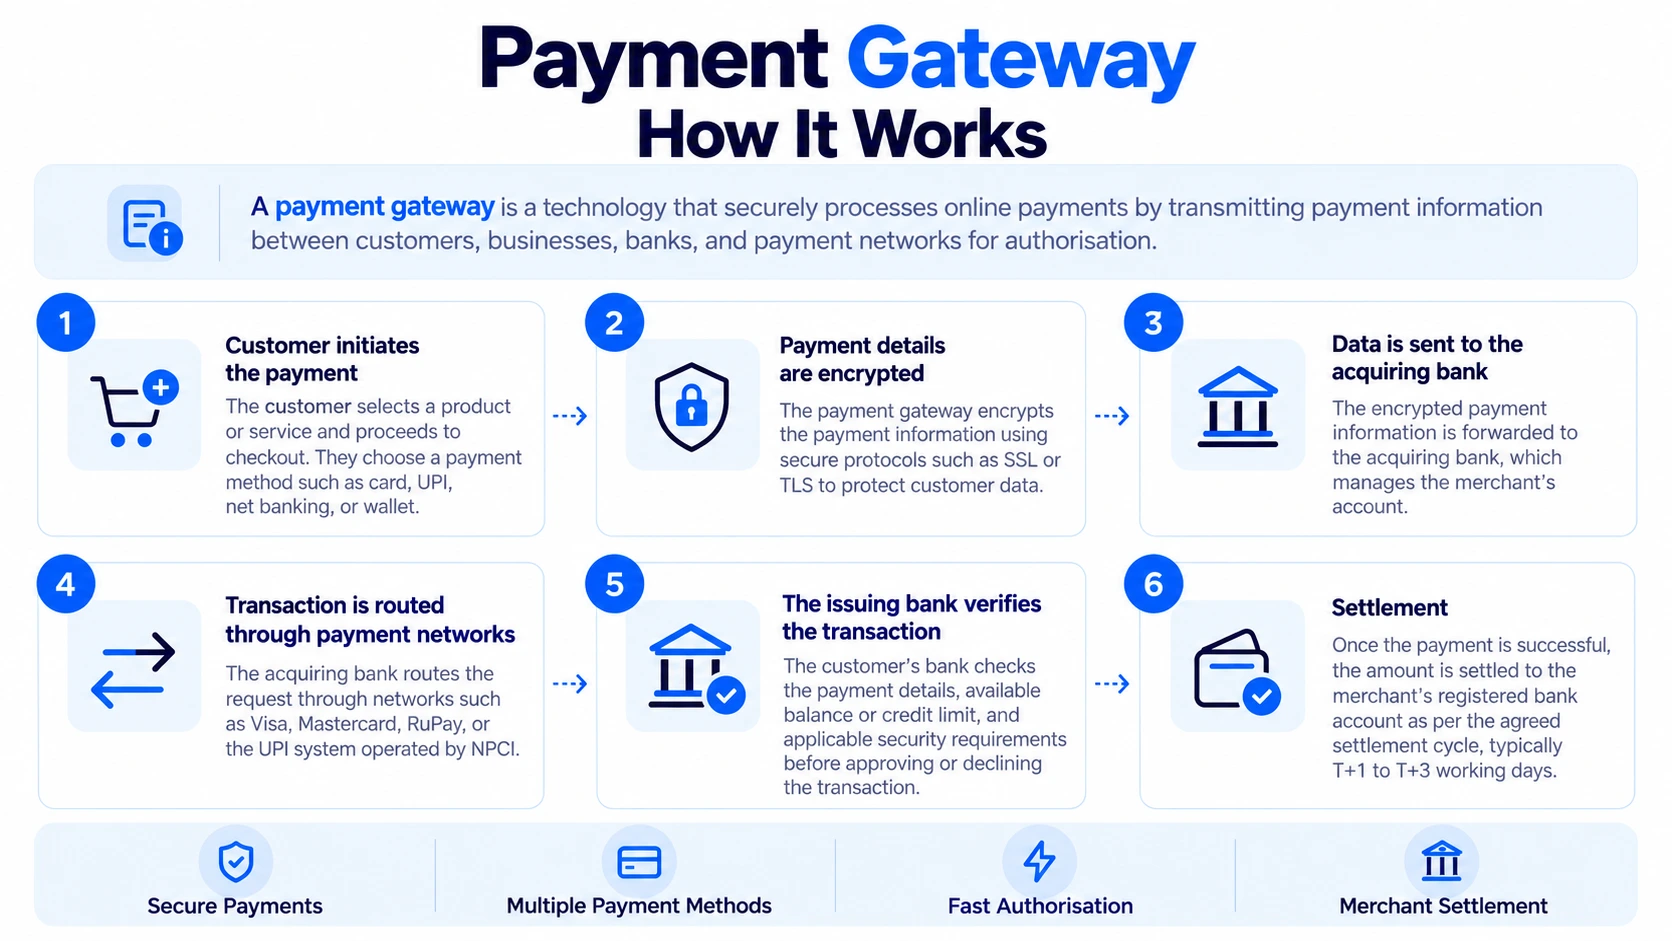
A payment gateway follows a structured process to ensure that online payments are processed securely and accurately. Each transaction passes through multiple systems before it is approved or declined.
Step-by-Step Payment Gateway Process
Step 1: Customer initiates the payment:
The customer selects a product or service on the website and proceeds to the checkout. At this stage, they choose a payment method such as a credit or debit card, UPI, net banking, or digital wallets.
Step 2. Payment details are encrypted:
Once the payment details are submitted by the customer, the payment gateway encrypts the payment information using secure protocols such as SSL or TLS. This prevents unauthorized access to sensitive data of the customer.
Step 3. Data is sent to the acquiring bank:
The encrypted payment information is forwarded to the acquiring bank, which is the bank that manages the merchant’s account.
Step 4. The transaction is routed through payment networks:
The acquiring bank routes the transaction request through relevant payment networks such as Visa, Mastercard, RuPay, or through the UPI system operated by NPCI, depending on the payment method used.
Step 5. The issuing bank verifies the transaction:
The customer's bank checks the payment details, available balance or credit limit, and applicable security requirements before approving or declining the transaction. The payment response is sent back through the payment network and gateway to the merchant, allowing the website or app to display the transaction status.
Step 6. Settlement:
Once the payment is successful, the payment aggregator collects the funds and settles the amount to the merchant’s registered bank account. The settlement timeline varies depending on the provider and payment method, typically ranging from T+1 to T+3 working days, as per the agreed settlement cycle.
Read More about: Working of Payment Gateway
Payment Gateway Examples
To understand how payment gateways are used in real business scenarios, here are a few common payment gateway examples across different use cases.
Website and E-commerce Payments
An online store uses a payment gateway to accept payments when customers complete a purchase. The gateway connects the checkout page to banks and payment networks, allowing the transaction to be authorized and completed securely.
Example: EnKash enables businesses to accept online payments through a single payment gateway that supports multiple payment modes. It integrates directly with websites and apps using APIs and plugins, while also offering real-time transaction visibility and compliant payment processing.
Subscription and SaaS Payments
SaaS platforms use payment gateways to collect recurring subscription payments. The gateway manages authorization, recurring mandates, and automated settlements without manual intervention.
Marketplaces rely on payment gateways to collect payments from customers and distribute funds to multiple sellers. The gateway ensures secure payment routing and accurate settlement across parties.
Service-Based Businesses
Service providers such as consultants, educators, and logistics companies use payment gateways to accept online payments through checkout pages or payment links.
Payment Gateway vs Payment Processing
Payment gateways and payment processing are closely connected but serve different roles in an online transaction. Understanding the difference helps businesses choose the right payment setup.
Payment Processing
Payment processing refers to the clearing, settlement, and movement of funds between the customer’s bank and the merchant’s bank after a transaction is authorized, involving acquiring banks, processors, and payment networks. This step is handled by payment processors and banking networks.
Key responsibilities of payment processing:
- Routes transactions through card networks or UPI systems.
- Transfers funds between issuing and acquiring banks
- Handles clearing, settlement, and reconciliation.
Key Differences
| Aspect | Payment Gateway | Payment Processing |
| Primary Role | Secures and authorizes payment data | Transfers funds between banks |
| Visibility | Visible during checkout | Occurs in backend systems |
| Function Focus | Data security and communication | Fund movement and settlement |
| Examples | EnKash, Razorpay | Visa, Mastercard, UPI systems |
Read More: What is the difference between Payment Gateway and Payment Processor
Types of Payment Gateways
Payment gateways can be grouped by how they are integrated into a website or application and by how much control the business has over the payment experience.
1. Hosted Payment Gateways
Hosted payment gateways redirect customers to a third-party payment page to complete the transaction. The gateway provider manages payment security and compliance. Best suited for: Small businesses and quick setups
Pros
- Easy to integrate
- Security and compliance handled by the provider
Cons
- Customer is redirected away from the merchant’s website
- Limited control over checkout experience
2. Self-Hosted Payment Gateways
Self-hosted gateways collect payment details directly on the merchant’s website and send them to the gateway for processing. Businesses have more control but also more responsibility. Best suited for: Large businesses with in-house technical teams
Pros
- Greater control over payment flow
- Better customization of checkout
Cons
- Higher security and compliance responsibility
- More complex implementation
3. API-Based Payment Gateways
API-based payment gateways allow businesses to embed payments directly into their website or app using APIs. Customers stay on the same page throughout checkout. Best suited for: SaaS platforms, marketplaces, and large e-commerce businesses
Pros
- Seamless checkout experience
- Supports multiple payment methods
- High level of customization
Cons
- Requires technical expertise
- Security compliance lies with the business
4. Bank Payment Gateways
Bank payment gateways are offered directly by banks and connect businesses to their banking infrastructure for online payments. Best suited for: Businesses that prefer direct bank integration and standardised payment flows
Pros
- Direct bank integration
- Strong security controls
Cons
- Longer onboarding process
- Limited flexibility and modern payment options
5. International Payment Gateways
International payment gateways support cross-border transactions and multiple currencies. Best suited for: Businesses serving global customers
Pros
- Multi-currency support.
- Global payment acceptance.
Cons
- Higher transaction and conversion fees.
- Additional compliance requirements.
Read more about Types of Payment Gateways in detail
Why Every Business Needs a Payment Gateway
Payment gateways help businesses collect payments online with security, speed, and reliability. As more customers prefer digital payment methods, a well-integrated payment gateway becomes essential for smooth checkout and consistent cash flow. For the following reasons, all merchants need a payment gateway:
- Secure transactions: To collect payments securely, as it encrypts payment data and reduces the risk of fraud during checkout.
- Multiple payment modes: Provide a choice to the customer to make payments through multiple payment methods like payment cards, UPI, net banking, and digital wallets, improving payment completion.
- 24×7 payment collections: Payment gateways allow merchants to accept payments 24x7, including weekends and holidays.
- Easy integration: Works with websites, apps, and e-commerce platforms through APIs or plugins.
Payment Gateway vs POS Terminal: Key Differences
A payment gateway and a POS (Point of Sale) terminal both help businesses accept digital payments, but they are used in different payment environments.
A payment gateway primarily enables online payments through websites, mobile apps, and e-commerce platforms. It securely transmits payment information to banks and payment networks for authorisation.
A POS terminal is a physical device used at retail stores, restaurants, and other business locations to accept in-person payments through debit cards, credit cards, and contactless payment methods.
Key Differences
| Feature | Payment Gateway | POS Terminal |
|---|
| Primary use | Online payment acceptance | In-person payment acceptance |
| Payment environment | Websites, mobile apps, and e-commerce stores | Retail stores, restaurants, and physical outlets |
| Payment methods | UPI, cards, net banking, and digital wallets | Chip cards, contactless cards, and NFC-enabled devices |
| Integration | APIs, SDKs, and e-commerce plugins | Physical device connected to a payment processing system |
| Customer interaction | Customers pay through an online checkout | Customers tap, insert, or swipe their cards at the terminal |
| Best suited for | Online businesses, e-commerce stores, and digital service providers | Retail outlets, restaurants, and other physical businesses |
How Much Does a Payment Gateway Cost in India?
Payment gateway charges in India vary depending on the provider, payment method, transaction volume, and services used. Most payment gateways charge a transaction fee, also known as the Merchant Discount Rate (MDR), for processing online payments.
Here are the common payment gateway fees businesses should consider:
- Setup Fees: A one-time charge for activating the payment gateway. Many providers offer free setup.
- Transaction Charges: A percentage of each successful transaction, depending on the payment method and provider's pricing plan.
- Annual Maintenance Charges: Some providers charge a recurring fee for maintaining the payment gateway service.
- Additional Charges: Fees may apply for international payments, chargebacks, instant settlements, or other services.
Note: Applicable GST may also be charged on payment gateway service fees.
When comparing payment gateway pricing in India, businesses should consider the total cost, including transaction fees, settlement charges, and any additional costs, rather than choosing a provider based only on the advertised transaction rate.
Learn more about payment gateway pricing in India.
What Happens When a Payment Gateway Transaction Fails or Remains Pending?
Not every payment receives an immediate success or failure confirmation. A transaction may fail because of incorrect payment details, insufficient funds, bank downtime, network interruptions, or authentication issues.
Sometimes, the customer completes the payment, but the merchant's website continues to show a pending status. This can happen when the final transaction response is delayed, or the payment notification does not reach the merchant's system.
Businesses should handle these situations by:
- Checking the transaction status: Verify the payment through the provider's transaction status API or dashboard before marking an order as paid.
- Using payment webhooks: Receive transaction updates from the payment gateway and process them reliably.
- Preventing duplicate orders: Use unique order references and idempotency controls to avoid processing the same payment or order more than once.
- Managing refunds: Confirm the actual transaction outcome before initiating a refund or asking the customer to retry.
- Reconciling transactions: Match successful payments, settlements, refunds, and bank credits to identify discrepancies.
A reliable payment gateway integration should handle successful, failed, and pending payments without relying only on what the customer sees on the checkout screen.
How to Choose the Right Payment Gateway in India
The best payment gateway depends on your business model, payment mix, and operational needs.
Criteria to Evaluate a Payment Gateway in India
- Payment methods supported: Cards, UPI, net banking, wallets, and international payments if required.
- Pricing and fees: Transaction charges, platform fees, and any settlement-related costs.
- Integration options: APIs, plugins (Shopify, WooCommerce), SDKs, and documentation quality.
- Settlement timeline: How quickly funds are credited to your account.
- Security and compliance: PCI DSS alignment, encryption, fraud checks, and risk controls.
- Support quality: Responsiveness during payment failures, disputes, and chargebacks.
Evaluate the best payment gateways in India.
Example Use Cases
- High UPI volume businesses: Choose a gateway optimized for UPI success rates and faster settlements.
- E-commerce stores: Prefer plugin support, multiple payment modes, and strong failure-handling flows.
- Subscription businesses: Look for recurring payment support and mandate management.
- Platforms and marketplaces: Prioritize multi-party settlement support and reconciliation visibility.
- Businesses using EnKash: If you want payment acceptance plus visibility and control across collections, EnKash can fit well as part of a broader payments and spend ecosystem.
Security and Compliance in Payment Gateways
Security and regulatory compliance are core requirements for any payment gateway. Since gateways handle sensitive financial data, they must follow strict standards to protect transactions and prevent fraud.
Key Security Measures Used by Payment Gateways
- Data Encryption: Payment gateways use SSL or TLS encryption to protect payment information while it is transmitted between the customer, merchant, and banks.
- Tokenization: Sensitive card details are replaced with secure tokens, ensuring that actual payment data is not stored or exposed during transactions.
- Authentication Controls: Mechanisms such as OTP-based verification, device checks, and risk-based authentication in payment gateways help prevent unauthorized payments.
- Fraud Monitoring: Payment gateways continuously monitor transactions for unusual patterns, failed attempts, and high-risk behavior to reduce fraud and chargebacks.
Compliance Standards in India
Payment gateways operating in India are required to comply with regulatory and industry standards, including:
Compliance ensures secure payment processing, customer data protection, and uninterrupted payment operations for businesses.
Payment Gateway vs Payment Aggregator
Payment gateways and payment aggregators are often used together, but they serve different roles in the payment ecosystem. The key difference lies in how merchants are onboarded, how payments are collected, and how settlements are handled.
Payment Gateway
In a payment setup, the payment gateway handles the technical flow of the transaction during checkout. It manages secure data transmission, encryption, and authorization by communicating with banks and payment networks. The gateway focuses on transaction security and approval, while other entities handle settlement and merchant management. Examples: EnKash, Razorpay, Stripe
Payment Aggregator
A payment aggregator simplifies payment acceptance by allowing multiple businesses to operate under a single master account. Instead of each merchant maintaining a direct relationship with a bank, the aggregator manages onboarding, compliance, risk checks, and settlements. This model reduces setup complexity and speeds up go-live for businesses. Examples: EnKash, Paytm, PhonePe, Easebuzz.
How the Two Work Together
In most setups, the payment gateway manages transaction authorization during checkout, while the aggregator handles merchant onboarding, pooled collections, and settlement to merchant accounts.
Key Differences: Payment Gateway vs Payment Aggregator
| Feature | Payment Gateway | Payment Aggregator |
|---|
| Primary role | Provides technology for securely transmitting and processing payment requests | Facilitates merchant onboarding and payment collection |
|---|
| Merchant onboarding | Depends on the provider and acquiring arrangement | Typically manages merchant onboarding and verification |
|---|
| Fund handling | A gateway acting only as a technology provider does not independently collect merchant funds | May handle funds through regulated settlement arrangements |
|---|
| Compliance | Depends on the services provided and applicable requirements | Subject to RBI requirements for regulated payment aggregators |
|---|
| Settlement | Supported through the relevant acquiring or payment provider arrangement | Facilitates merchant settlement under applicable regulations |
|---|
| Business use | Provides payment integration infrastructure | Simplifies payment acceptance for eligible merchants |
|---|
A single payment service provider can offer both payment gateway technology and payment aggregation services. The distinction is based on the functions performed, not necessarily on two different companies.
How to Integrate a Payment Gateway on a Website
Integrating a payment gateway into a website follows a structured process that ensures secure payment collection and smooth transaction handling.
Step-by-Step Payment Gateway Integration Process
1. Choose a payment gateway
Select a payment gateway based on supported payment methods, transaction fees, security standards, settlement timelines, and ease of integration.
2. Register as a merchant
Sign up with the chosen payment gateway and complete the merchant onboarding process. This usually involves submitting business details, bank account information, and required KYC documents such as PAN and GST.
3. Integrate using APIs or plugins
Payment gateways provide different integration options:
- API integration for custom-built websites and applications
- Plugins or extensions for platforms such as Shopify, WooCommerce, Magento, and other CMS tools
4. Test transactions
Use the gateway’s sandbox or test environment to simulate transactions. This helps confirm that payment flows, error handling, and security measures are working as expected.
5. Go live and monitor payments
After successful testing, switch to live mode. Use the payment gateway dashboard to track transactions, settlements, and failed payments, and to monitor for potential issues.
The Parties in the Payment Gateway Ecosystem
A payment gateway ecosystem involves multiple parties working together to complete a secure online transaction. Each participant plays an important role in the payment flow:
1. Customer (Payer): The customer is the one who initiates the payment—whether by card, UPI, wallet, or net banking. This is the person-to-merchant transaction, where money flows from the buyer to the seller.
2. Merchant (Payee): The merchant is the business or seller receiving the payment. For e-commerce or SaaS businesses, the merchant payment gateway ensures they can accept and manage online transactions seamlessly.
3. Payment Gateway: The gateway online system captures the customer’s payment details, encrypts them, and routes them securely to the banks for authorization.
4. Acquiring Bank (Merchant’s Bank): This is the bank that holds the merchant account. It receives the transaction request from the payment gateway and forwards it to the payment processor.
5. Issuing Bank (Customer’s Bank): The issuing bank provides the card or account used for payment. It verifies the details, checks the balance, and approves or declines the transaction.
6. Payment Processor / Card Network: Payment processors and card networks help route transaction information between the acquiring bank and issuing bank. Card networks such as Visa, Mastercard, RuPay, and American Express support card-based transactions.
Get Started with EnKash Payment Gateway
Accept online payments securely and simplify payment collection with EnKash Payment Gateway. Designed for businesses of all sizes, EnKash supports multiple payment methods, including UPI, credit cards, debit cards, net banking, and digital wallets, through a single payment integration.
With pre-built checkout, APIs, SDKs, and e-commerce plugins, businesses can integrate the payment gateway into their websites, mobile apps, or online stores. EnKash also offers transaction tracking, settlement visibility, and reconciliation tools to help businesses manage payments efficiently.
Whether you're launching an online store or scaling an existing business, EnKash provides flexible payment gateway integration options to meet your business needs.
Conclusion
Payment gateways play a central role in enabling secure and efficient online transactions. They connect customers, businesses, and banks, ensuring that payment data is protected, authorized, and processed with accuracy. From accepting card and UPI payments to supporting e-commerce, subscriptions, and service-based transactions, payment gateways have become essential infrastructure for digital businesses. Choosing the right payment gateway depends on factors such as payment methods supported, security standards, integration flexibility, and settlement timelines. A well-integrated payment gateway improves the checkout experience, reduces payment failures, and supports business growth as digital payments continue to expand across India and global markets.
FAQs
1. What is a payment gateway?
A payment gateway enables secure online payments by handling authorization and communication between customers, merchants, and banks.
2. How does a payment gateway work?
A payment gateway authorizes payments securely during checkout and communicates the transaction result to both the merchant and the customer.
3. How to integrate a payment gateway in a website?
Payment gateways can be integrated using APIs for custom-built websites or plugins for platforms like Shopify, WooCommerce, and Magento. After integration, businesses test transactions in sandbox mode before going live.
4. Which payment gateway is best in India?
The best payment gateway depends on business needs such as payment modes, settlement speed, pricing, and integration flexibility. Popular options in India include EnKash, Razorpay, Paytm, and Cashfree.
5. How to add a payment gateway to a website?
To add a payment gateway, businesses must select a provider, complete merchant onboarding, integrate APIs or plugins, test payment flows, and activate live transactions.
6. How to get a payment gateway?
Businesses can apply directly on a payment gateway provider’s website by submitting business and bank details and completing the required verification process.
7. What is a UPI payment gateway? A UPI payment gateway enables real-time bank-to-bank payments using UPI IDs or QR codes.