Key Takeaways
- A Gift PPI is regulated under RBI's prepaid payment instrument framework. A gift card usable only with the merchant that issues it may qualify as a closed-system instrument, which does not require RBI authorisation as a payment system.
- The maximum value of a Gift PPI is ₹10,000 per instrument, and it cannot be reloaded.
- Cash withdrawal and ordinary fund transfer are unavailable. The balance may move back to the source account with the holder’s consent.
- The PPI issuer must maintain the purchaser's KYC details. RBI does not require a separate KYC exercise when the Gift PPI is issued against a debit to the purchaser's bank account or credit card in India. Applicable KYC and anti-money-laundering obligations continue to apply.
- RBI permits Gift PPI issuers to offer interoperability, but does not mandate it. Actual acceptance depends on the issuer, the instrument's form and applicable payment-network arrangements.
- RBI requires at least one year of validity and allows revalidation when the holder requests it.
- RBI does not mandate additional-factor or two-factor authentication for Gift PPI transactions. However, issuers and participating payment networks may apply security and authentication controls appropriate to the instrument.
Gift cards can look similar in form, even when the regulatory and usage rules behind them are different. A retailer-only card and an RBI-regulated Gift PPI in India can both carry prepaid value, but they do not have the same regulatory status. These rules matter to businesses purchasing Gift PPIs and to recipients using or redeeming them. This blog explains the current position on value, KYC, use, expiry, refunds, issuer status, security, and customer rights.
What Is a Gift PPI Under RBI Rules?
A Gift PPI is a prepaid payment instrument issued for gifting stored monetary value under RBI’s PPI framework. The purchaser pays for the Gift PPI in advance, and the recipient uses the stored value to make eligible merchant payments. Banks need RBI approval to issue PPIs, while non-bank issuers need RBI authorization. Unlike a closed-system merchant gift card, a regulated Gift PPI is issued under RBI's PPI framework. Whether a gift card qualifies as a regulated PPI depends on how it is issued, funded, and accepted, not simply on its product name.
Is Every Gift Card a Gift PPI?
The term ‘gift card’ can refer to different types of prepaid products. A store may issue value that works only with that merchant, while an authorized PPI issuer may offer a prepaid gift instrument under RBI rules.
| Feature | RBI-Regulated Gift PPI | Closed-System Store Gift Instrument |
|---|
| Regulatory status | Covered by RBI PPI rules | Outside RBI PPI authorisation framework |
| Issuer | Bank or RBI-authorised non-bank PPI issuer | Merchant selling its own goods or services |
| Where it works | Within the permitted acceptance arrangement | With the issuing merchant only |
| Third-party payments | May be supported within its structure | Cannot pay unrelated third-party merchants |
| RBI approval | Required for the PPI issuer | Not required merely for the closed system |
RBI treats a closed-system instrument usable only with the issuing entity as outsie the regulated payment-system category.
How Does a Gift PPI Work?
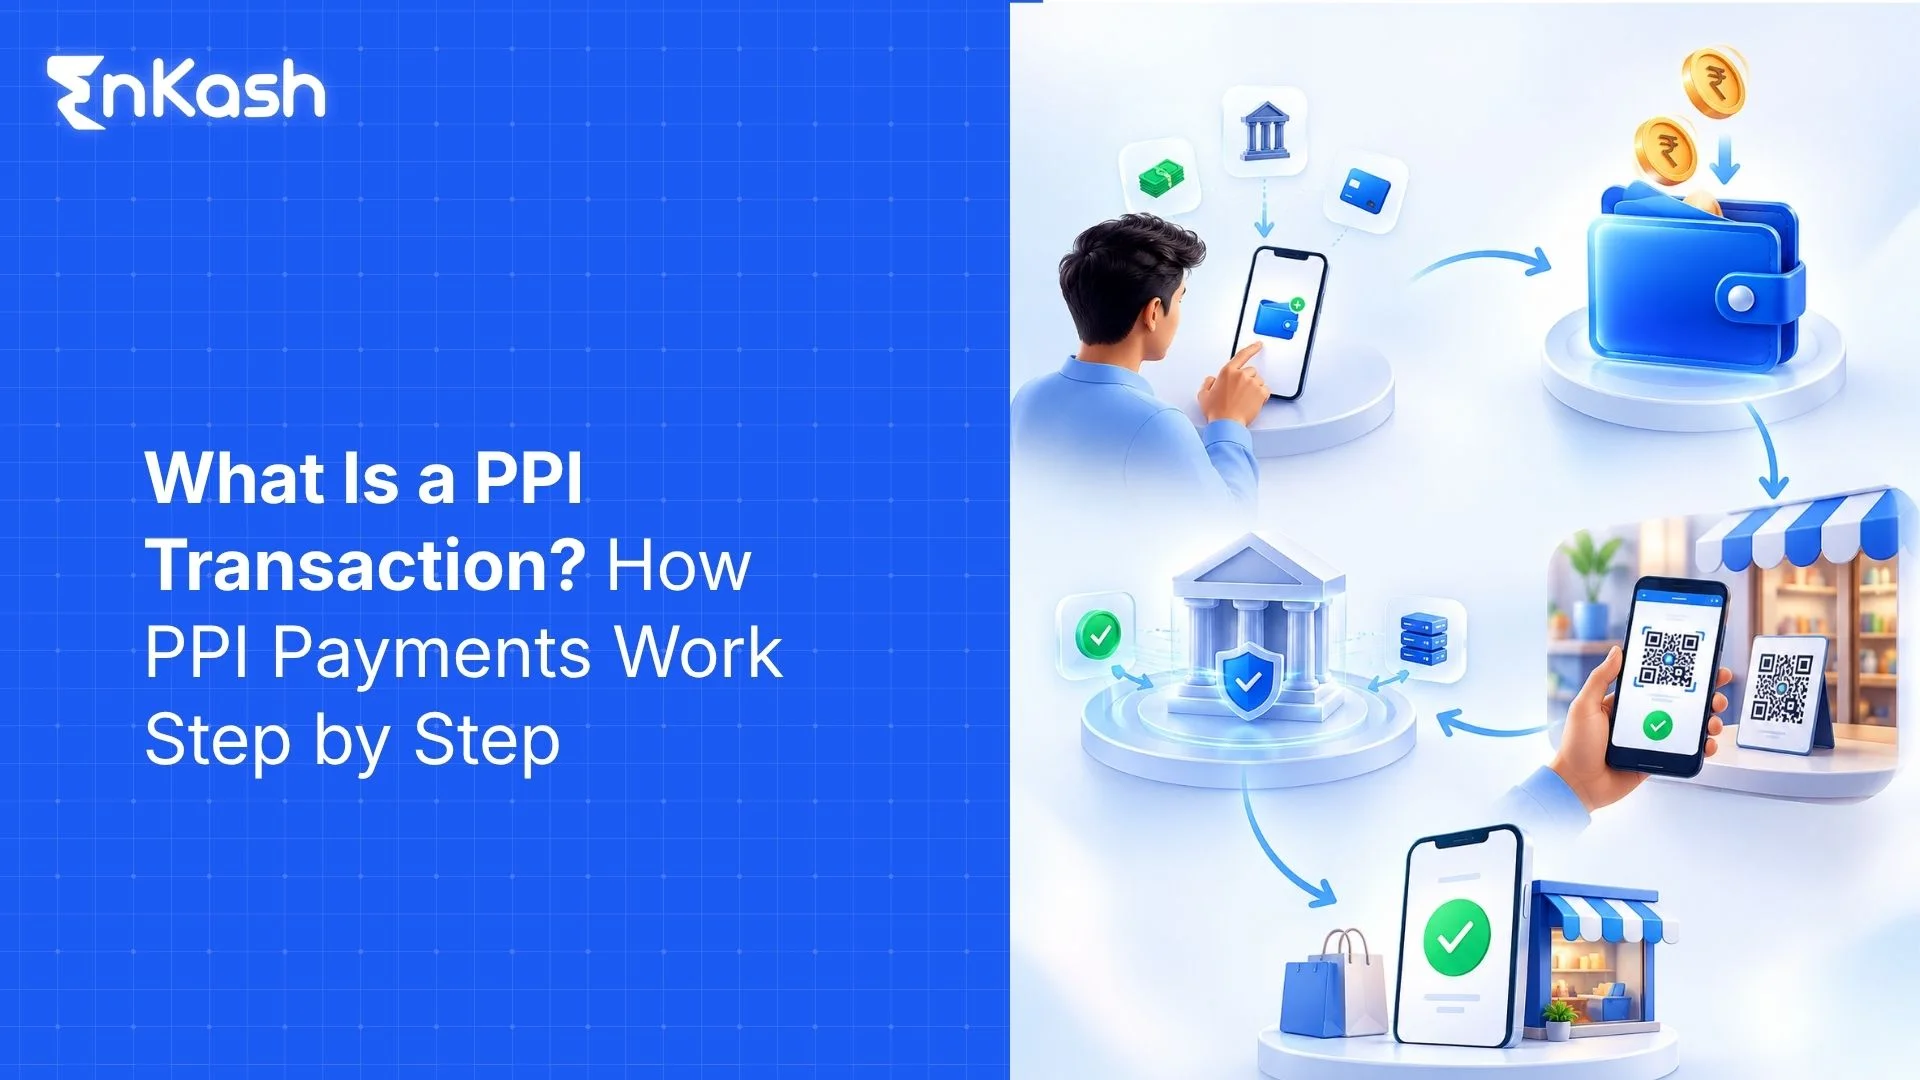
A Gift PPI typically involves an issuer, a purchaser, and a recipient. The purchaser and recipient may be different people. The purchaser pays for the Gift PPI in advance, and the recipient uses the prepaid balance for eligible purchases. A typical Gift PPI moves through these stages:
- The purchaser obtains the instrument:
A purchaser obtains the Gift PPI from an RBI-authorised issuer or through its authorised distribution channel. - The issuer creates the prepaid instrument:
The issuer records the prepaid value against the Gift PPI, which the holder accesses through a card, wallet or another permitted electronic form. - The Gift PPI is delivered to the recipient:
RBI recognizes that the intended beneficiary can become the holder even when someone else paid for it. - The holder makes an eligible purchase:
The stored value is used with a merchant available under the issuer’s acceptance arrangement. - The available balance is updated:
Each eligible purchase reduces the available balance. Any remaining value can be used for subsequent purchases, subject to validity and issuer terms.
What Are the RBI Limits and Usage Restrictions for Gift PPIs?
Under RBI's operative PPI directions, the maximum value of a Gift PPI is ₹10,000 per instrument. RBI also restricts how the value can be used or moved.
| Rule | Current RBI Position |
|---|
| Maximum value | ₹10,000 per Gift PPI |
| Reloading | Not permitted |
| Cash withdrawal | Not permitted |
| Regular fund transfer | Not permitted |
| Return of unused value | Permitted back to the original funding account with the holder's consent |
| Interest on balance | Not permitted |
| Purchaser KYC | Issuer must maintain purchaser KYC details |
| Separate KYC | Not required when issuance is funded by debit to the purchaser's Indian bank account or credit card |
| Minimum validity | One year from loading |
| Revalidation | Required when requested by the holder |
| Interoperability | Optional for the issuer |
| Two-factor authentication | Not mandatory under the Gift PPI provision |
| Number of instruments per purchaser | Determined through the issuer's Board-approved risk-based policy |
| Issuer | RBI-approved bank or RBI-authorised non-bank PPI issuer |
RBI permits outstanding value to return to the source account with the holder’s consent. This is a specific balance-return mechanism, separate from ordinary cash-out or person-to-person transfer.
What KYC Is Required for a Gift PPI in India?
The Gift PPI KYC rule is frequently oversimplified. A buyer may see a short digital purchase flow and assume that KYC does not apply. RBI takes a more specific approach. The issuer must maintain purchaser KYC details, while a separate-KYC exemption applies in a defined funding situation.
Purchaser KYC Details
The issuer must maintain KYC details of the purchaser. General anti-money-laundering and related PPI obligations also continue to apply.
Separate-KYC Exemption
A fresh KYC exercise is unnecessary when the Gift PPI is issued against a debit to the purchaser’s Indian bank account or credit card.
Purchaser and Holder
The buyer and holder may be different people. RBI recognizes the intended beneficiary as a possible holder even when another person bought the instrument.
Where Can a Gift PPI Be Used?
A Gift PPI does not automatically work at every merchant. Where a Gift PPI can be used depends on the issuer's merchant acceptance arrangements and the payment networks supported by the instrument.
Eligible Merchants
The merchant needs to participate in the relevant issuer or payment arrangement.
RBI permits PPIs as cards, wallets, and other electronic forms used to access stored value. Paper vouchers cannot be issued as PPIs.
Spending Restrictions
Merchant categories and transaction rules may differ by product. The issuer’s terms show where the value can be spent.
Is Interoperability Mandatory for Gift PPIs?
Gift PPI interoperability is optional for issuers. Interoperability means compatibility across payment systems. RBI separately mandates it for qualifying Full-KYC PPIs, while a Gift PPI issuer may choose whether to provide it. A card-form product that supports interoperability must follow the applicable authorized card-network standards. Electronic form alone does not mean the instrument works across every UPI app or card network.
How Long Is a Gift PPI Valid
Gift PPIs have separate RBI requirements for validity, expiry notifications, revalidation, and inactivity.
Minimum Validity
Under RBI's validity requirements applicable to Gift PPIs, the instrument must have a validity period of at least one year from loading. Issuers may provide a longer validity period. Because Gift PPIs cannot be reloaded, the one-year minimum validity period is measured from the initial loading.
Expiry Warning and Revalidation
The issuer must warn the holder at reasonable intervals during the 45 days before expiry. When a Gift PPI holder requests revalidation, the issuer must provide it, including by issuing a new instrument where necessary. Revalidation does not permit additional loading of value.
Inactivity
A PPI with no financial transaction for one consecutive year becomes inactive after notice. Reactivation requires validation and applicable due diligence.
What Happens to Refunds and Unused Gift PPI Balances
A Gift PPI may have unused value because the recipient has not spent the full amount, a purchase was cancelled, or the instrument has expired. RBI specifies different treatment for these situations.
| Situation | Applicable treatment |
|---|
| An eligible payment fails or is cancelled | The amount originally debited from the PPI must be returned to that PPI under the applicable refund rules. |
| A recipient wants to transfer unused value | The funds may be transferred back to the original source account with the holder's consent. |
| A Gift PPI expires with unused balance | The holder can request revalidation, including issuance of a replacement instrument where necessary. |
| The holder requests a refund after expiry | For non-bank-issued PPIs, RBI provides for payment into a bank account under its expired-balance rules. |
| A Gift PPI remains inactive for one year | The issuer must provide notice before making it inactive. Reactivation requires applicable validation and due diligence. |
These rules are distinct. A refund for a cancelled purchase should not be confused with transferring unused gift value to another account.
Who Can Issue a Gift PPI in India
The brand displayed on a Gift PPI is not necessarily the name of the RBI-authorised issuer. Customers should verify the issuing entity before purchasing or using a Gift PPI:
Bank Issuers
Banks need RBI approval to issue PPIs.
Non-Bank Issuers
A non-bank company needs RBI authorization under the Payment and Settlement Systems framework.
Co-Branded Gift PPIs
A commercial brand may appear with the product, while the authorized issuer remains responsible for regulatory and customer-service duties. RBI requires the issuer’s name to be prominently visible.
Verify the Issuer
RBI publishes lists of approved bank and non-bank PPI issuers. Verify the issuing entity against RBI's published lists rather than relying solely on the brand displayed on the instrument.
What Security Rules Apply to Gift PPIs
Although RBI does not mandate two-factor authentication for Gift PPIs, issuers must still implement security and fraud-prevention controls.
2FA and AFA
RBI says two-factor authentication or an additional factor of authentication is not mandatory for Gift PPI transactions.
Fraud and Risk Monitoring
Issuers remain responsible for fraud prevention, information security, and transaction monitoring.
PPI issuers also need mechanisms for transaction information and balance visibility under the framework.
What Rights Does a Gift PPI Holder Have if Something Goes Wrong
Gift PPI holders are entitled to the customer-service and grievance-redressal protections applicable under RBI's PPI framework. Holders can approach the issuer for unauthorised transactions, expired instruments, missing refunds and transaction records. RBI requires issuers to provide the following customer protections:
Clear Terms and Charges
Issuers must disclose applicable fees, charges, validity periods and expiry conditions in simple language.
Complaint Access
The issuer must maintain a publicly disclosed grievance-redressal process, an escalation mechanism and a facility for tracking complaints.
Resolution Timeline
RBI requires PPI issuers to initiate action on complaints promptly, preferably within 48 hours, and endeavour to resolve them within 30 days of receipt.
Transaction Records
Issuers must provide a facility for holders to obtain account statements covering at least the preceding six months, along with transaction history for at least ten transactions.
Ombudsman Recourse
Eligible customers can use the Reserve Bank Integrated Ombudsman framework after the applicable complaint path.
What Should You Check Before Buying a Gift PPI?
Before purchasing a Gift PPI for personal or corporate gifting, verify the issuer and the terms of the instrument.
- Issuer: Confirm which RBI-approved bank or authorised non-bank entity issues the Gift PPI.
- Value: Check that each instrument is within the ₹10,000 regulatory ceiling.
- Acceptance: Verify where the instrument can be used and whether it supports the relevant payment network.
- Validity: Check the expiry date and the process for requesting revalidation.
- KYC: Understand which purchaser details the issuer requires and whether the separate-KYC exemption applies.
- Refunds: Review the procedures for failed payments, unused balances and transfers back to the original funding source.
- Support: Confirm the issuer's customer-service contact information, grievance process and applicable charges.
For businesses purchasing Gift PPIs in bulk, it is also important to understand issuance limits, recipient delivery, distribution records and the issuer's risk-based controls.
FAQs
Can a Gift PPI Be Issued as a Paper Voucher?
RBI permits PPIs in cards, wallets, and other allowed electronic forms. A retailer may still sell a paper gift voucher under another commercial arrangement, but that does not make the voucher a PPI.
Can a Gift PPI Be Used Outside India?
The standard domestic Gift PPI framework does not provide a general overseas-payment facility. RBI's specified outward cross-border PPI permission applies to eligible Full-KYC PPIs issued by authorised banks, subject to FEMA and other applicable conditions. The RBI provisions allowing specified outward cross-border PPI payments apply to eligible bank-issued Full-KYC PPIs, not automatically to Gift PPIs.
Can a Business Buy Several Gift PPIs for Employees or Customers?
RBI does not set one universal fixed count. The issuer decides the number available to a purchaser through a Board-approved risk-based approach. Corporate buyers can face issuer-specific quantity or transaction controls.
Can Gift PPI Value Earn Interest?
No. RBI does not permit PPI issuers to pay interest to holders on their prepaid balances.
Can Unused Gift PPI Balance Be Returned to a Bank Account?
Yes. RBI permits outstanding Gift PPI value to be returned to the original source account with the holder’s consent. This is different from ordinary fund transfer, which is not permitted for Gift PPIs.
Does a Gift PPI Require Two-Factor Authentication?
Two-factor authentication is not mandatory for Gift PPI transactions under RBI rules. The issuer still has to maintain fraud controls, transaction monitoring, and other security measures required under the PPI framework.
What Happens When a Gift PPI Expires?
A Gift PPI can be revalidated when the holder requests it. RBI also requires issuers to warn holders before expiry, and separate rules apply to any balance that remains after the instrument expires.
Can a Gift PPI Be Used More Than Once?
Yes, a Gift PPI may be used for multiple eligible purchases while sufficient value remains available, subject to the issuer's transaction rules. Non-reloadable means that additional money cannot be added after issuance. It does not necessarily mean that the instrument can be used for only one purchase.
Can a Gift PPI Be Used at Any Store in India?
No. A Gift PPI can be used only at merchants supported by the issuer's acceptance arrangements or applicable interoperable payment networks. RBI permits issuers to offer interoperability for Gift PPIs, but does not make it mandatory. Customers should verify acceptance before purchasing or using the instrument.