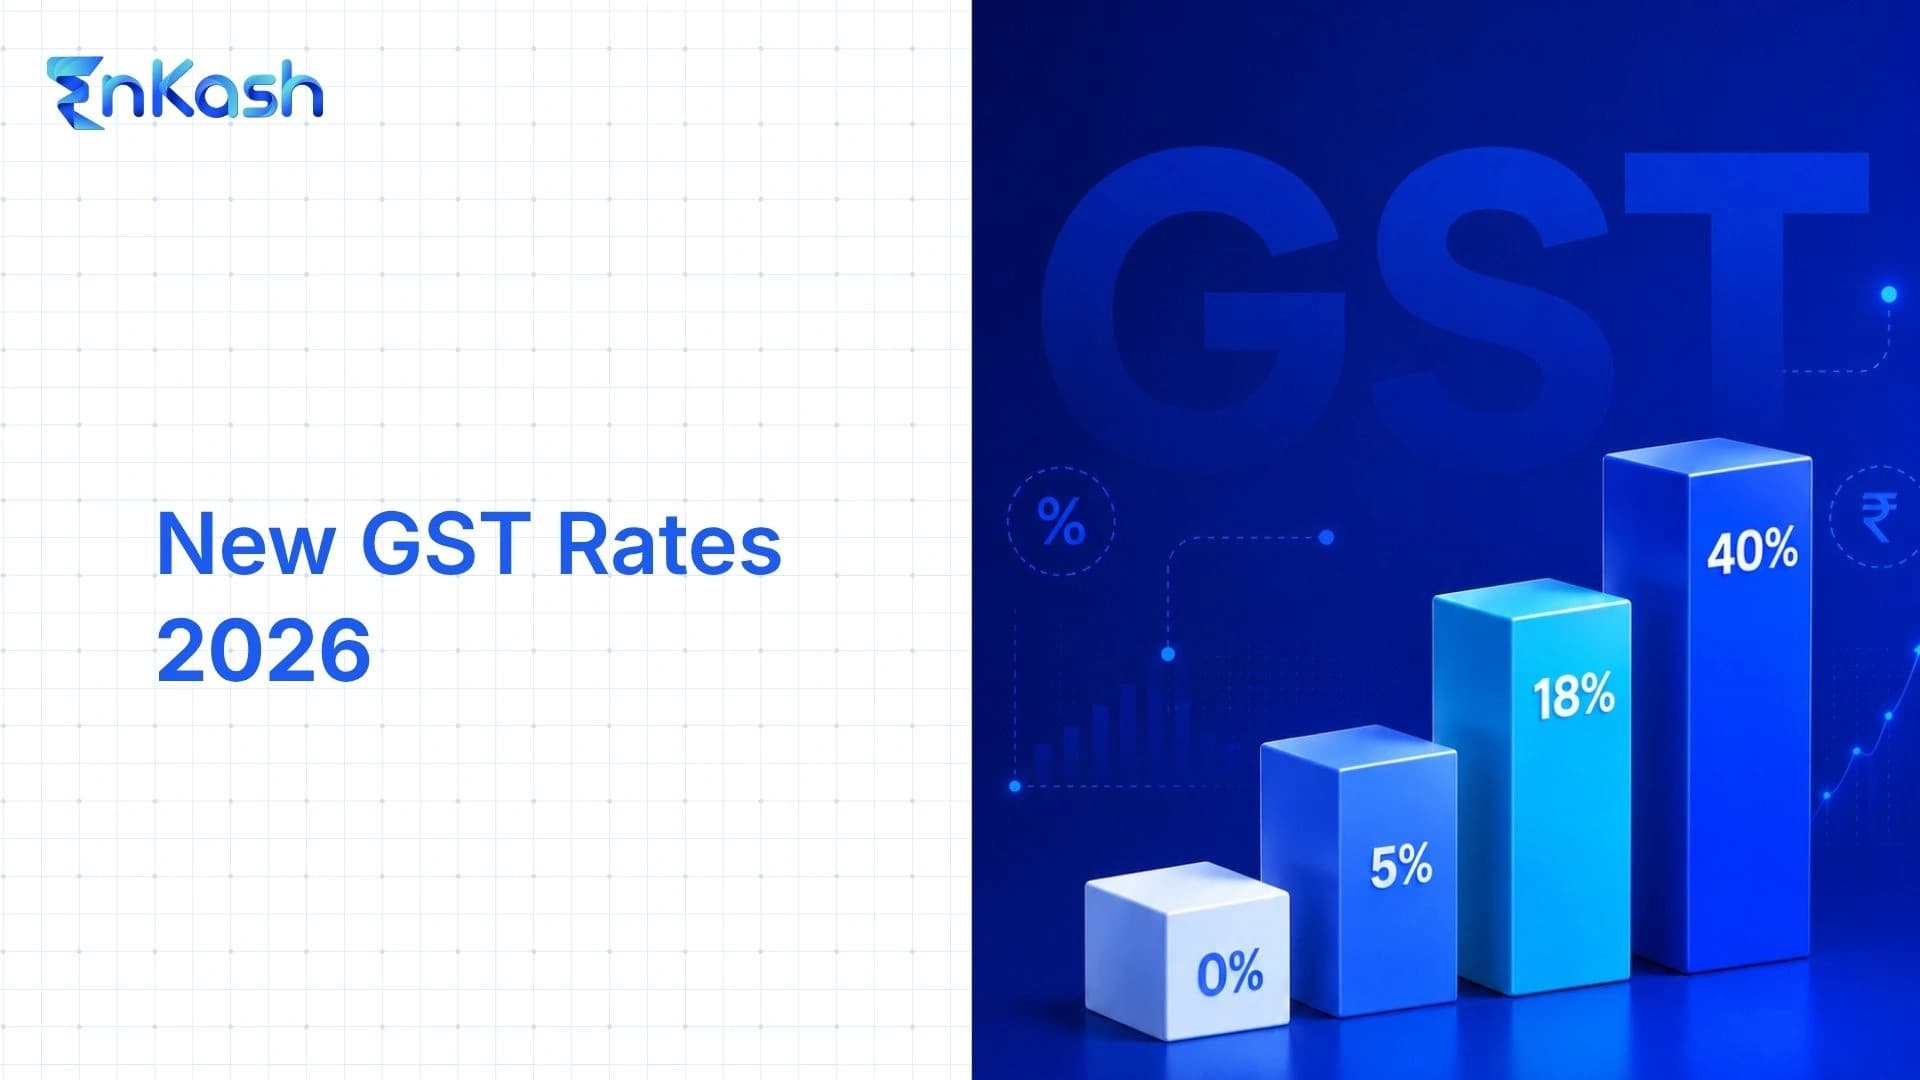
GST rates in India have been changed after the 56th GST Council meeting in September 2025. The old four-tier structure was simplified into two main rates: a 5% merit rate and an 18% standard rate, along with a special 40% rate for specified goods and services.
Nil-rated and exempt supplies continue, while special rates such as 3%, 1.5% and 0.25% still apply to certain goods including precious metals and diamonds.
Most of the revised rates took effect from 22 September 2025. The tax treatment of specified pan masala and tobacco products changed later, from 1 February 2026.
This guide explains the current GST rates in India in 2026, the different types of GST rate slabs, what changed after the 2025 reforms, and how businesses can identify the correct GST rate for goods and services.
The broad GST rate structure in India in 2026 consists of a 5% merit rate, an 18% standard rate, and a special 40% demerit rate. Nil/exempt supplies and special rates such as 3%, 1.5% and 0.25% also continue for specified goods.
What Is a GST Rate?
A GST rate is the percentage of Goods and Services Tax charged on the taxable value of a good or service.
For example, if a taxable service worth ₹10,000 attracts 18% GST, the GST amount is ₹1,800.
The rate that applies depends on the classification of the good or service, relevant HSN or SAC code, exemptions, and the latest government notifications.
To understand more, read EnKash’s What is GST? guide.
What Are the Types of GST Rates in India?
The current GST structure should not be described simply as four slabs because some supplies fall under special rates. A more accurate way to understand the types of GST rates in India in 2026 is:
| GST Rate | Broad Treatment | Common Examples |
|---|
| Nil / Exempt | No GST charged on specified supplies | UHT milk, specified medicines, Indian breads, individual life and health insurance |
| 5% | Merit rate | Many everyday goods, packaged foods, agricultural equipment and specified services |
| 18% | Standard rate | Most taxable goods and services, electronics, professional services and many industrial products |
| 40% | Special demerit rate | Specified luxury, gaming, beverage, vehicle and tobacco categories |
| 3% | Special rate | Gold, silver, platinum and specified jewellery |
| 1.5% | Special rate | Specified cut and polished diamonds |
| 0.25% | Special rate | Rough diamonds and specified precious stones |
The GST Council described the 2025 reform as a two-rate structure built around 5% and 18%, with a special 40% rate. Other special rates continue outside those main slabs.
Source: GST Council - 56th GST Council Meeting recommendations
Are 0% GST, Exempt Supply and Zero-Rated Supply the Same?
No. These terms are often grouped together in general rate lists, but their GST treatment is different.
An exempt supply includes supplies attracting a nil rate or otherwise exempt from GST. A zero-rated supply generally refers to exports and supplies to SEZ developers or units and has different input-tax-credit treatment.
Source: GST Council - Zero rating of supplies
The 56th GST Council meeting approved one of the biggest rate rationalisations since GST was introduced.
| Earlier Structure | Current Structure |
|---|
| 5% | 5% merit rate |
| 12% | Most affected supplies moved to 5% or another notified rate |
| 18% | 18% standard rate |
| 28% | Most affected supplies moved to 18% or 40% |
| Compensation cess on specified demerit goods | Structure changed for several categories |
| Special rates | Some special rates continue |
The changes for most goods and services became effective on 22 September 2025.
The reform did not mean that every product previously taxed at 12% automatically became 5%, or every product at 28% automatically became 18%. The applicable rate depends on the individual tariff entry and notification. Businesses should check the specific HSN or SAC classification rather than relying on a broad product category.
Current GST Rate List in India for 2026
Nil GST and Exempt Supplies
Several goods and services were moved to nil or exempt treatment as part of the 2025 reforms. Examples include:
| Product or service | Current treatment |
|---|
| UHT milk | Nil |
| Pre-packaged and labelled chena or paneer | Nil |
| Chapati, roti, paratha and parotta | Nil |
| Maps, charts and globes | Nil |
| Pencils, sharpeners, crayons and pastels | Nil |
| Exercise books and notebooks | Nil |
| Specified life-saving medicines | Nil |
| Individual life insurance policies | Exempt |
| Individual health insurance policies | Exempt |
For more detail on exempt supplies, read EnKash’s GST Exemptions guide.
5% GST Rate
The 5% rate acts as the main merit rate under the rationalised GST structure. Many goods that previously attracted 12% or 18% moved to 5%.
| Category | Examples |
|---|
| Personal care | Hair oil, toilet soap bars, shampoo, toothbrushes, toothpaste |
| Food | Butter, ghee, packaged namkeen, sauces, pasta, instant noodles and several processed foods |
| Household goods | Bicycles, tableware and kitchenware |
| Agriculture | Tractors and specified agricultural machinery |
| Healthcare | Many medicines, diagnostic kits and medical devices |
| Hospitality | Hotel accommodation valued up to ₹7,500 per unit per day, without ITC |
| Personal services | Specified gyms, salons, barbers and yoga services |
Is Every Essential Product Taxed at 5%?
No. Some essential goods are exempt or nil-rated, while others attract 5%. The exact GST rate depends on the product’s classification, packaging, description, and applicable notification. Avoid deciding the GST rate only from a broad description such as “food,” “medicine,” or “household item.”
18% GST Rate
The 18% rate is the main standard GST rate in the current structure. Many goods that previously attracted 28% were moved to 18%, while a large number of services already taxed at 18% remained there.
| Category | Examples |
|---|
| Consumer electronics | Televisions, air conditioners and dishwashers |
| Construction | Cement |
| Automobiles | Qualifying small cars |
| Two-wheelers | Motorcycles up to 350cc |
| Commercial vehicles | Buses, trucks, ambulances and three-wheelers |
| Automobile parts | Auto parts covered by the uniform 18% treatment |
| Business services | Many professional, consultancy and IT services |
| Electronics | Mobile phones and several electronic products |
40% GST Rate
The 40% rate is a special demerit rate rather than the standard rate for ordinary goods and services. It applies to specified categories such as:
| Category | Examples |
|---|
| Vehicles | Larger and specified luxury passenger vehicles |
| Motorcycles | Motorcycles above 350cc |
| Beverages | Specified aerated, caffeinated and carbonated beverages |
| Personal-use transport | Certain personal aircraft and yachts |
| Gaming and betting | Casinos, betting, gambling and specified actionable claims |
| Tobacco-related goods | Pan masala, cigarettes and specified tobacco products from February 2026 |
Special GST Rates That Still Apply
The 3% GST rate has not disappeared. Some goods continue to use special GST rates outside the main 5%, 18% and 40% structure.
- 3% GST
The 3% rate continues to apply to specified precious metals and jewellery, including gold and silver. - 1.5% GST
Specified cut and polished diamonds are subject to a special 1.5% GST rate. - 0.25% GST
Specified rough diamonds and precious stones can attract the concessional 0.25% GST rate.
GST Rates on Common Goods and Services in 2026
Users frequently search for GST rates on individual products rather than searching by HSN code. Here is a quick reference for some commonly searched categories:
| Product or service | GST rate / treatment |
|---|
| Mobile phones | 18% |
| Air conditioners | 18% |
| Televisions | 18% |
| Cement | 18% |
| Small qualifying cars | 18% |
| Motorcycles up to 350cc | 18% |
| Motorcycles above 350cc | 40% |
| Gold | 3% |
| UHT milk | Nil |
| Pre-packaged paneer | Nil |
| Individual life insurance | Exempt |
| Individual health insurance | Exempt |
| Hotel accommodation up to ₹7,500 per unit per day | 5% without ITC |
| Hotel accommodation above ₹7,500 | 18%, subject to applicable ITC rules |
| Most stand-alone restaurant services | 5% without ITC |
| Restaurants in specified hotel premises | 18% with ITC, subject to prescribed conditions |
Restaurant GST does not depend simply on whether the restaurant is air-conditioned. Stand-alone restaurants generally attract 5% without ITC, while different rules apply to restaurants in specified hotel premises.
How HSN and SAC Codes Determine GST Rates
A GST rate should ideally be identified from the classification of the actual supply. HSN codes classify goods, while SAC codes classify services.
Two products that sound similar in everyday language may have different classifications, exemptions, or conditions. For example, different dairy products can have different GST treatment. UHT milk and specified paneer may be nil-rated, while butter, ghee and cheese can attract 5%.
Businesses should:
- Identify the correct product or service description.
- Find the applicable HSN or SAC classification.
- Check the latest CBIC/GST notification for that classification.
- Confirm any conditions, exemptions or ITC restrictions.
- Apply the GST rate to the taxable value.
CBIC maintains a rate-search facility for goods and services. For more details, read EnKash’s HSN code in the GST guide.
GST Rate vs Types of GST: What Is the Difference?
These two terms are frequently confused. GST rates tell you how much tax applies, such as 5%, 18% or 40%. Types of GST tell you which GST component applies, such as CGST, SGST, UTGST or IGST.
For example, an 18% intra-state transaction may generally be split into 9% CGST + 9% SGST. An eligible inter-state transaction at the same rate may instead attract 18% IGST. The overall GST rate remains 18%; only the tax component changes.
For a complete explanation, read Types of GST: CGST, SGST, IGST and UTGST.
How to Calculate GST Using the Applicable Rate
Once you know the correct GST rate, the tax calculation is straightforward.
For an amount that does not include GST:
GST amount = Taxable value × GST rate ÷ 100
If a service costs ₹10,000 and attracts 18% GST: GST = ₹10,000 × 18 ÷ 100 = ₹1,800. Total = ₹11,800.
When the price already includes GST, the calculation is different. Instead of calculating it manually each time, use the EnKash GST Calculator to calculate inclusive and exclusive GST amounts and see the tax breakdown.
How to Check the Correct GST Rate for a Product or Service
Do not rely entirely on a generic GST rate list when preparing an actual invoice. A product’s GST treatment can depend on factors such as:
| Factor | Why it matters |
|---|
| HSN/SAC classification | Determines the applicable tariff entry |
| Product description | Similar products can have different rates |
| Packaging | Some food products differ based on packaging or labelling |
| Value thresholds | Apparel, footwear, hotels and other categories may use value conditions |
| End use | Some concessions depend on use |
| Notification date | GST rates can change |
| Exemption conditions | A rate may apply only when specified conditions are met |
For high-value or unclear transactions, businesses should verify the latest CBIC/GST notification or consult a qualified GST professional before raising the invoice.
Why Businesses Need to Track GST Rate Changes
An incorrect GST rate affects more than the final invoice amount. It can create problems with tax liability, input tax credit, customer invoices, returns, and reconciliation.
For businesses selling hundreds or thousands of products, rate changes should therefore be updated across accounting software, ERP systems, billing tools and product masters. The HSN/SAC classification stored in these systems should also be reviewed when the underlying tax notification changes.
For more information about credit treatment, read EnKash’s Input Tax Credit in GST guide.
What Changed in the 56th GST Council Meeting?
The 56th GST Council meeting held on 3 September 2025 approved the rate rationalisation that shaped the current GST structure. Major changes included:
Moving to 5% and 18% as the two main GST rates
Introducing a 40% special demerit rate
Removing GST on specified essential goods and medicines
Exempting individual health and life insurance
Moving many everyday products to 5%
Moving several consumer durables and vehicles from 28% to 18%
Reducing cement from 28% to 18%
Reducing eligible hotel accommodation to 5% without ITC
Introducing several procedural and compliance reforms
Most rate changes took effect from 22 September 2025.
For the full policy update, read EnKash’s 56th GST Council meeting key updates.
Key Takeaways
India’s GST rate system is simpler than it was before September 2025, but it is not accurate to say that every transaction now falls only under 5%, 18% or 40%.
The main structure consists of the 5% merit rate, 18% standard rate and 40% special demerit rate. Nil and exempt supplies also exist, while special rates such as 3%, 1.5% and 0.25% continue for specified products.
Businesses should identify the correct HSN or SAC classification before applying a rate. When a notification changes, product masters, invoices, and accounting systems should be updated as well.
For actual tax calculations, enter the applicable rate into the EnKash GST Calculator.
FAQs
1. What are the current GST rates in India in 2026?
The main GST structure uses 5% and 18%, with a special 40% demerit rate. Nil/exempt supplies and special rates such as 3%, 1.5%, and 0.25% also continue for specified goods.
2. What are the types of GST rates?
The broad categories include nil/exempt supplies, the 5% merit rate, the 18% standard rate, the 40% demerit rate and special rates for specified goods such as precious metals and diamonds.
3. Are the 12% and 28% GST slabs still applicable in 2026?
The 2025 rate rationalisation removed the earlier 12% and 28% structure for most affected supplies, moving them to other notified rates. Businesses should check the current HSN/SAC entry rather than applying the old slab automatically.
4. Is 3% GST still applicable in India?
Yes. The 3% special GST rate continues for specified precious metals and jewellery. It was not abolished by the 2025 rate rationalisation.
5. What is the GST rate on mobile phones?
Mobile phones generally attract 18% GST in India. The applicable classification should still be checked against the current HSN entry before invoicing.
6. What is the GST rate on restaurant food?
Most stand-alone restaurant services attract 5% GST without ITC. Restaurant services supplied from specified hotel premises can attract 18% with ITC, subject to the applicable rules.
7. What is the GST rate on hotel rooms?
Hotel accommodation valued up to ₹7,500 per unit per day attracts 5% GST without ITC. Accommodation above ₹7,500 generally attracts 18%, subject to the applicable conditions.
8. What is the GST rate on gold?
Gold and specified precious metals continue to attract a special 3% GST rate. Jewellery manufacturing or other associated services can have separate treatment.
9. Which items attract 40% GST?
The 40% rate applies to specified demerit and luxury categories such as larger vehicles, motorcycles above 350cc, certain beverages, gaming-related supplies, and specified tobacco products.
10. How can I find the GST rate using an HSN code?
Identify the correct HSN code for the product and search the current CBIC GST rate schedule or notification. Do not rely only on an old rate list because classifications and rates can change.